Expectation vs. Reality: Why the Real Stress in Buying a Home Isn't the Process, It's the Surprise
Have you ever been told something would take a week, and then it took a month? On a recent episode of the Lofty Lender Home Buyer Education podcast, hosts Kyle Guldenpfennig and Charlie Chedester dug into a theme that shows up constantly in both the mortgage process and everyday life: expectation versus reality, and why the gap between the two is what actually causes stress, not the process itself.
Here's a breakdown of the conversation, and what it means for anyone buying, selling, or refinancing right now.
An Extra Day Is Forgivable. An Extra Week Is Not.
Charlie opened the episode with a simple observation: when you're told one thing and it takes an extra day, most people are pretty forgiving. When it takes two, three, four days, or you never hear back at all, it's a completely different experience, even if the underlying task wasn't actually that much harder. The frustration rarely comes from the delay itself. It comes from not knowing what to expect in the first place.
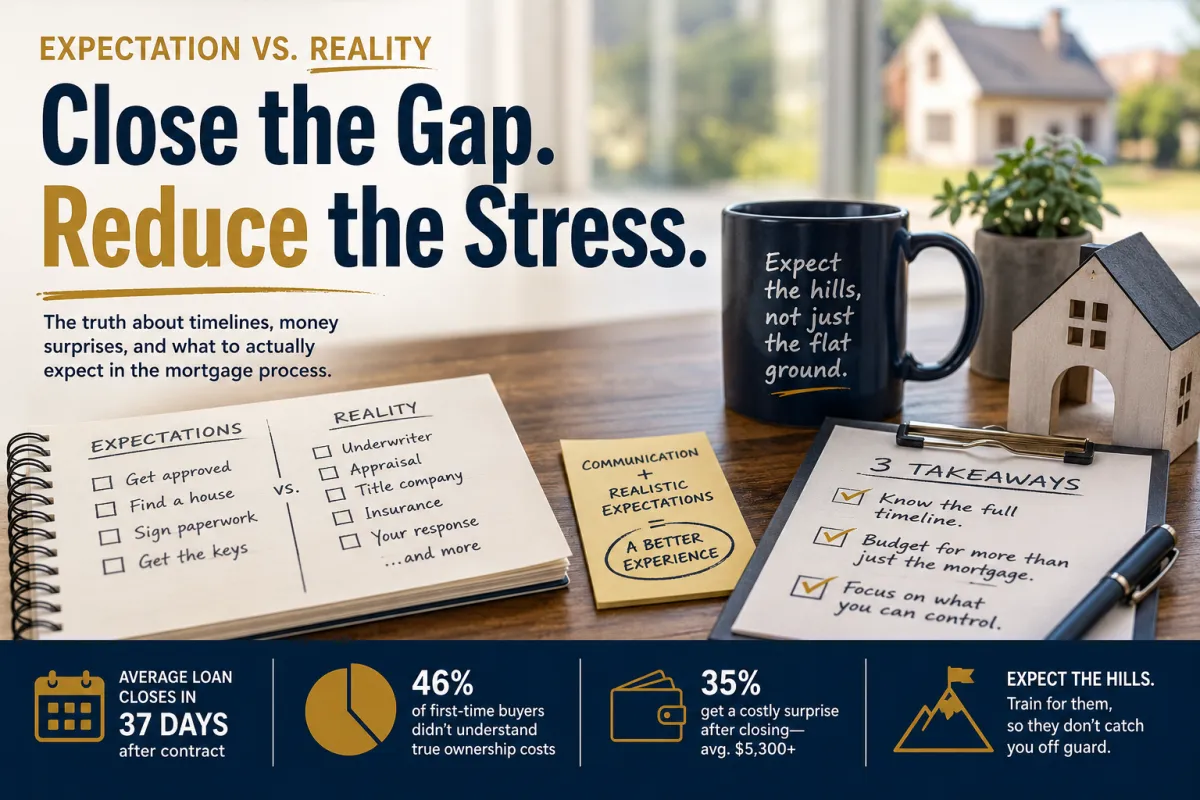
That idea runs through the entire mortgage process. Most buyers walk in thinking it's simple: get approved, find a house, sign the paperwork, get the keys. In reality, there's an underwriter, an appraiser, a title company, and often an insurance agent, all with their own timelines and dependencies. Kyle and Charlie can't hand every buyer a list of every possible thing that could go wrong, that would overwhelm anyone, but they can set a realistic expectation up front and ask buyers to respond quickly when something is needed from them. As Charlie put it, if a buyer takes a week to respond to a request, they've delayed everyone else who's dependent on that answer, from the lender to the insurance agent to the title company.
The Numbers Behind the Stress
Kyle shared some statistics that back this up. According to a Zillow article, the average home loan closes in about 37 days once a contract is signed. Team Chedester can close as quickly as 10 days in the right circumstances, but averages don't tell the whole story. Closings get delayed by finance-related snags, a low appraisal, missing insurance paperwork, a credit change nobody catches until underwriting flags it, or a job change that comes up out of nowhere.
On the money side, close to half of first-time buyers, 46%, say they didn't fully understand that homeownership costs more than just the mortgage payment. About a third, 35%, get hit with a costly surprise after closing, averaging over $5,300. That's exactly why Kyle and Charlie build their closing cost estimates a little conservatively. If a buyer is told they need $10,000 and it turns out to be $9,500, that feels like a win. If they're told $10,000 and it turns into $15,000, that's a completely different, much worse experience, even though the actual dollar swing might be similar in either direction.
Kyle's Own Surprise, After Closing on His Own Sale
Kyle isn't immune to this either. After moving out of his old house, his water heater sprang a leak. Separately, he'd hired someone to fill cracks in his driveway and sidewalk as part of a home inspection item he'd agreed to split with the buyer, but the contractor only quoted and completed the driveway, missing the sidewalk entirely, which was actually the bigger issue. Kyle had to call them back out, and ended up covering that cost himself since the original quote wasn't accurate. The bill arrived after he'd already closed on the house.
As Charlie pointed out, none of it was a huge deal in the grand scheme of things, but the emotional weight of an unexpected bill showing up after you think you're done is real. It's a good reminder that even people who work in the industry every day aren't exempt from being caught off guard by the unexpected.
The Marathon Analogy: Train for the Hills, Not Just the Flat Ground
Kyle offered an analogy that stuck: imagine training for a marathon by only ever running the flat parts of the course. You'd finish training feeling ready. But the first hill on race day, an appraisal that comes in low, a furnace that dies in month two, is going to hurt a lot more than it should, simply because nobody warned you it was coming.
Buyers who go in expecting a few hills tend to handle them just fine. Buyers who expect flat ground the whole way are the ones who end up panicking. That's exactly why setting proper expectations up front is such a core part of how Kyle and Charlie work with clients.
Under-Promise and Over-Deliver: A Lesson from the COVID Refi Boom
Charlie and Kyle both pointed back to a lesson learned during the refinance boom, when call volume was overwhelming and they couldn't always get back to people within their usual couple of hours. Instead of promising a fast turnaround they couldn't guarantee, they started telling everyone up front it would take a week to hear back.
Kyle was initially uncomfortable with that, it felt wrong to tell someone he'd take a week to respond. But almost everyone who heard that expectation was fine with it, and when Kyle got back to them in three or four days instead, they were thrilled. Meanwhile, the few people he'd told "I'll get back to you tomorrow" and then didn't, because he was slammed, were the ones sending frustrated follow-ups all day. Same workload, completely different experience, entirely because of how the expectation was set at the start.
Mortgage Rates: What the News Gets Wrong
Freddie Mac tracks mortgage rates weekly, and as of this episode, the 30-year fixed is sitting right around 6.67% nationally, basically flat from the week before, though a touch higher than this time last year at 6.58%. Freddie Mac's own economists note that affordability has genuinely improved compared to a year ago, largely because home prices have been correcting, or "right-sizing," in a lot of markets, rather than climbing the way they had been.
Kyle flagged a common source of confusion: news articles reporting that "rates improved today" are almost always reporting data collected a week earlier. By the time it hits the headlines, the actual number has often already moved again. If rate movement is genuinely the deciding factor for you, the better move is talking directly with your lender rather than reacting to a headline, since rates are rarely the only thing that matters anyway. As Charlie put it, between sale prices and interest rates, everybody knows there's an equation, they just don't always know all the pieces that go into it.
The Furniture Story That Started This Episode
The story that prompted this whole conversation: Kyle recently ordered two couches from a local furniture store. He was told four to six weeks for delivery, and that he'd put down a 25% deposit with the balance due at pickup, or in this case, delivery. A few weeks later, he added a couple of barstools and chairs to the order and checked in on the timeline, still within that four-to-six-week window.
By the end of week seven, his wife called the store and learned the furniture had actually arrived, but they don't deliver to their area until the end of week eight or the beginning of week nine. On top of that, the store had charged the full amount up front on Kyle's credit card, despite telling him it would only be a 25% deposit.
Kyle's takeaway: if he'd been told from the start it would be four to eight weeks, landing at eight weeks wouldn't have bothered him at all, that would have felt like a win. Instead, being told four to six weeks and landing at nine turned a totally normal furniture delivery timeline into a frustrating experience. It wasn't really about how long it took. It was about the gap between the promise and what actually happened.
Three Actionable Takeaways
Kyle and Charlie closed the episode with three concrete steps for anyone buying, selling, or refinancing right now.
1. Ask your lender for the "what could go wrong" version of your timeline, not just the best-case version. You don't need to walk through every extreme what-if scenario, but knowing that appraisals, title work, or insurance documentation are common holdups up front means a hiccup feels like a normal step instead of a crisis.
2. Budget for ownership costs, not just the mortgage payment. Set aside a cushion for maintenance, a higher-than-expected utility bill, or a repair the inspection didn't catch. Home warranties have become less common than they used to be, but Kyle still recommends them. If nothing breaks in year one, you've paid for cheap peace of mind. If something does, you'll be glad you had it.
3. Separate the parts of the process you can control from the parts you can't. You can control how prepared your paperwork is and how quickly you respond to requests. You can't control rate movement or another buyer's offer coming in while you're waiting to sell. Spending your energy on the first category takes a lot of the sting out of the second.
The Bottom Line
Most of the stress in buying a home doesn't come from the process itself, it comes from the gap between what you expected and what actually happened. Close that gap ahead of time, with a lender who tells you the honest timeline instead of the exciting one, and the mortgage process starts to feel a lot more manageable, life changes and all.
Listen to the Full Conversation
This article covers the highlights, but the full episode goes deeper into real client stories, this week's rate update, and exactly how Kyle and Charlie approach setting expectations with every client. Search for The Lofty Lender with #TallMoneyMan wherever fine podcasts are downloaded to listen to the complete episode and catch every future one.
Wondering what to actually expect on your own timeline? Reach out to your Lofty Lender team, we're happy to walk you through it.